
Fee-Only vs. Fee-Based Financial Advisors: What's the Difference?
If you're comparing a fee-only and a fee-based financial advisor, the most important difference is how they are compensated.
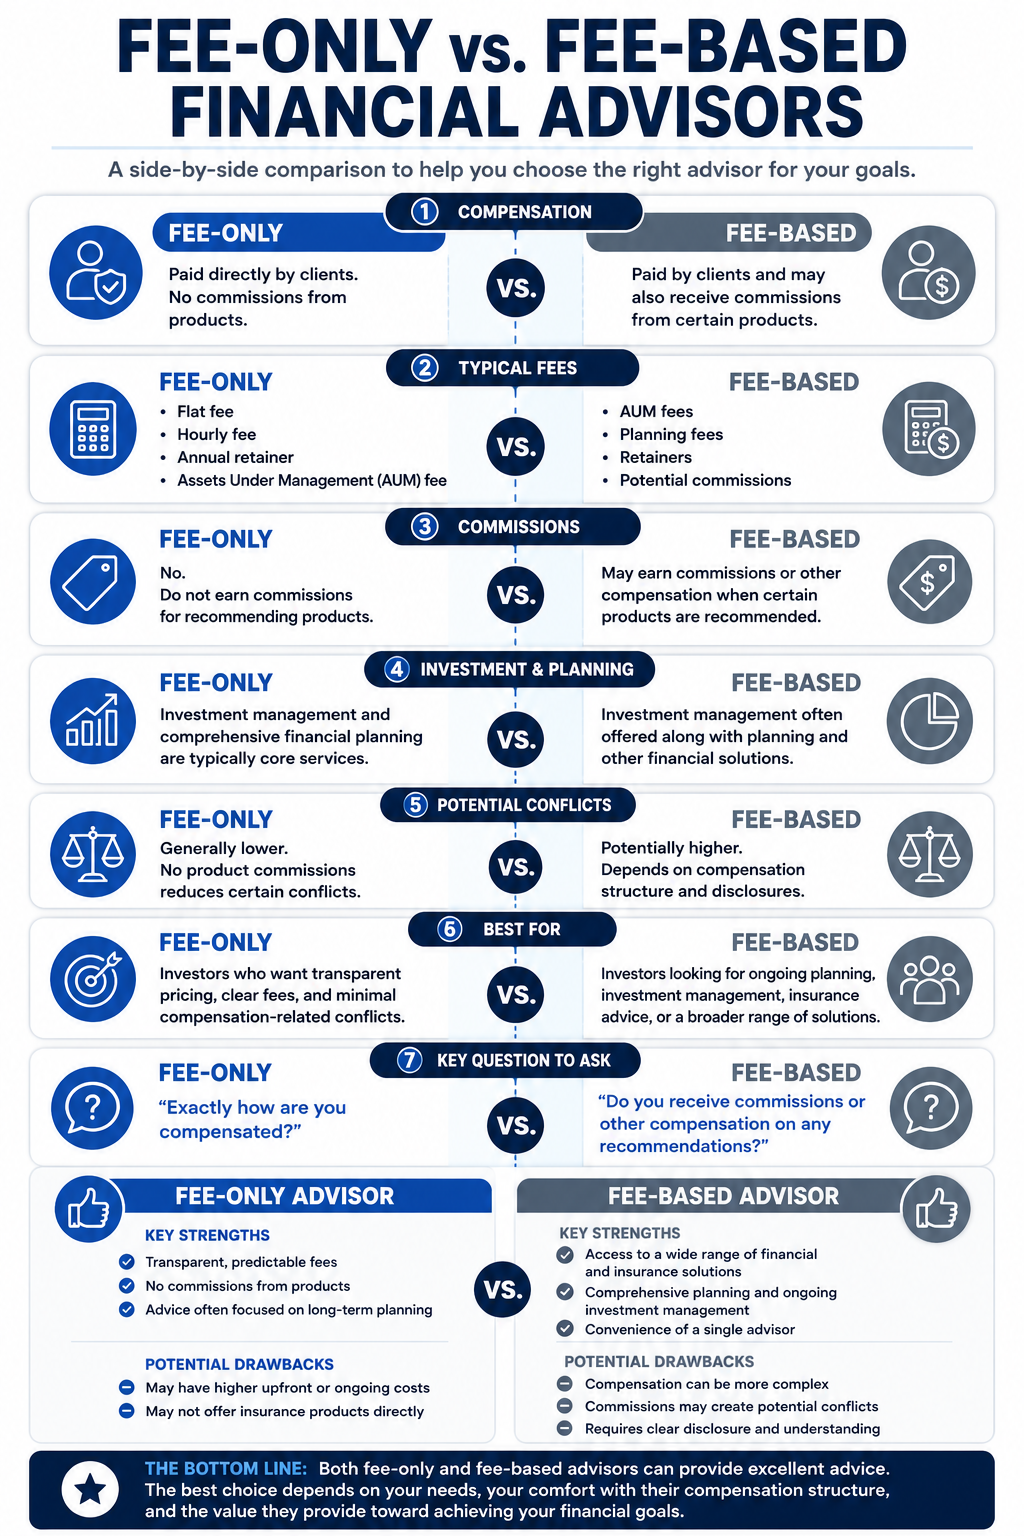
A fee-only financial advisor is paid directly by their clients. Compensation typically comes from flat fees, hourly fees, annual retainers, or a percentage of assets under management (AUM). They do not receive commissions for recommending investment or insurance products.
A fee-based financial advisor also charges fees to clients but may earn commissions or other compensation when clients purchase certain financial or insurance products. Not every fee-based advisor earns commissions, but the compensation structure allows for the possibility.
Neither model is automatically better.
The right choice depends on your financial situation, the services you need, and how comfortable you are with each advisor's compensation structure.
If your priority is paying directly for advice without product commissions, a fee-only advisor may be a better fit. If you need comprehensive planning, ongoing investment management, or specialized insurance advice, a fee-based advisor may also be an excellent choice. Provided you understand how the advisor and their firm are compensated.
The key is understanding exactly how your advisor gets paid before making a decision.
A note on terminology: “Fee-only” and “fee-based” describe compensation approaches, but these labels alone don't tell you an advisor's registration, licensing, credentials or regulatory obligations. Always ask an advisor what credentials and registrations they hold, what they're licensed to provide, and exactly how they're compensated.
Key Takeaways
Looking for an Advisor Who Matches Your Preferences?
Choosing between a fee-only and fee-based advisor is only one part of the decision. Every financial situation is different.
Answer a few quick questions and we'll match you with a financial advisor whose services, experience, and compensation model fit your needs.
The Ultimate Fee-Only vs. Fee-Based Comparison
At a glance: Both fee-only and fee-based financial advisors can provide valuable financial advice. The key difference is how they are compensated. Understanding these differences can help you choose the advisor who best aligns with your financial goals and preferences
Don't Judge an Advisor by Their Compensation Model Alone
One of the biggest misconceptions in financial planning is that fee-only advisors are always better than fee-based advisors.
In reality, an advisor's compensation model is only one factor to consider.
The best advisor for you should also have:
- Relevant experience with people in a similar financial situation
- A planning philosophy that aligns with your goals
- Clear and transparent communication
- A compensation structure you understand
- Services that match your needs
An exceptional fee-based advisor may provide significantly more value than a mediocre fee-only advisor, and vice versa.
The goal isn't to find the "best" compensation model.
The goal is to find the best advisor for your unique situation.
Key Insight
Think of compensation as one question in your advisor selection process, not the entire decision.
Ask yourself:
- Do I understand how this advisor is paid?
- Am I comfortable with that compensation structure?
- Do the services I receive justify the cost?
- Do I trust the advisor's recommendations?
If the answer to those questions is yes, you've likely found a strong advisor regardless of whether they are fee-only or fee-based.
What Is a Fee-Only Financial Advisor?
A fee-only financial advisor is compensated exclusively by their clients. Instead of earning commissions from investment funds, insurance products, or other financial products, fee-only advisors are paid directly for the advice and services they provide.
Depending on the advisor or firm, compensation may be structured in several ways, including:
- A flat fee for a financial plan
- An hourly consulting rate
- An annual retainer
- A percentage of assets under management (AUM)
Although these fee structures differ, they all have one thing in common: the client, not a product provider, is the source of the advisor's compensation.
Because fee-only advisors do not typically receive commissions for recommending financial products, many investors view this compensation model as highly transparent. Clients generally know what they are paying, why they are paying it, and how the advisor is compensated.
However, transparency should not be confused with lower cost.
A fee-only advisor charging 1% annually on a $2 million portfolio will likely cost significantly more than an advisor charging a one-time flat planning fee. The compensation model simply explains how an advisor is paid, not whether their services represent good value.
Ultimately, the quality of advice depends on far more than compensation alone. Experience, expertise, communication, and the advisor's planning process often have a greater impact on long-term outcomes than the fee model itself.
Common Fee-Only Compensation Models
Fee-only advisors may use one or more of the following pricing structures.
Flat Fee
A fixed amount charged for a specific engagement, such as developing a comprehensive financial plan. The cost typically remains the same regardless of investment portfolio size.
Best suited for: Individuals looking for one-time financial planning or a second opinion.
Hourly Fee
Clients pay only for the advisor's time, similar to working with an accountant or lawyer.
Best suited for: People with specific financial questions who don't require ongoing advice.
Annual Retainer
A recurring annual fee that covers ongoing planning, meetings, and financial advice throughout the year.
Best suited for: Individuals and families seeking continuous financial planning without tying costs directly to investment balances.
Assets Under Management (AUM)
The advisor charges a percentage of the assets they manage on your behalf, typically calculated annually.
As your portfolio grows, the advisor's compensation generally increases as well.
Best suited for: Investors looking for ongoing portfolio management combined with comprehensive financial planning.
Advantages of Choosing a Fee-Only Advisor
Many Canadians prefer fee-only advisors because of several potential benefits:
- Transparent compensation that's easy to understand.
- No commissions earned from selling investment or insurance products.
- Advice often centered on long-term financial planning.
- Compensation is generally straightforward to explain.
- May reduce certain compensation-related conflicts of interest.
Potential Drawbacks
Fee-only advisors aren't automatically the best choice for everyone.
Potential considerations include:
- Comprehensive planning can involve a significant upfront or ongoing cost.
- Some advisors have minimum asset requirements.
- Insurance recommendations may require coordination with a licensed insurance professional if the advisor doesn't offer those products directly.
- Paying directly for advice may feel unfamiliar to investors accustomed to commission-based relationships.
The Bottom Line
A fee-only advisor is paid directly by the client, not by commissions on financial products. Many investors appreciate the transparency this provides, but a fee-only compensation model does not automatically mean better advice or lower overall costs.
The right advisor is one who clearly explains their compensation, provides services that match your needs, and delivers value that justifies the fee.
What Is a Fee-Based Financial Advisor?
A fee-based financial advisor charges clients for financial advice and investment management but may also receive commissions or other compensation from certain financial or insurance products when appropriate.
This is where many investors become confused.
The term fee-based is often mistaken for fee-only, but they are not the same thing.
Like fee-only advisors, fee-based advisors frequently charge:
- A percentage of assets under management (AUM)
- Financial planning fees
- Annual retainers
- Flat planning fees
The difference is that fee-based advisors may also be compensated through commissions on certain products or services they recommend.
For example, if a client requires permanent life insurance, disability insurance, or another commission-paying product, the advisor may receive compensation from the product provider in addition to the fee charged to the client.
Receiving a commission doesn't automatically mean a recommendation is inappropriate. However, commissions and other compensation arrangements can create potential conflicts of interest. Clients should understand how the advisor is compensated, what potential conflicts exist, and how those conflicts are addressed.
The important question isn't simply "Does this advisor earn commissions?"
It's:
"How is this advisor compensated, and am I comfortable with that arrangement?"
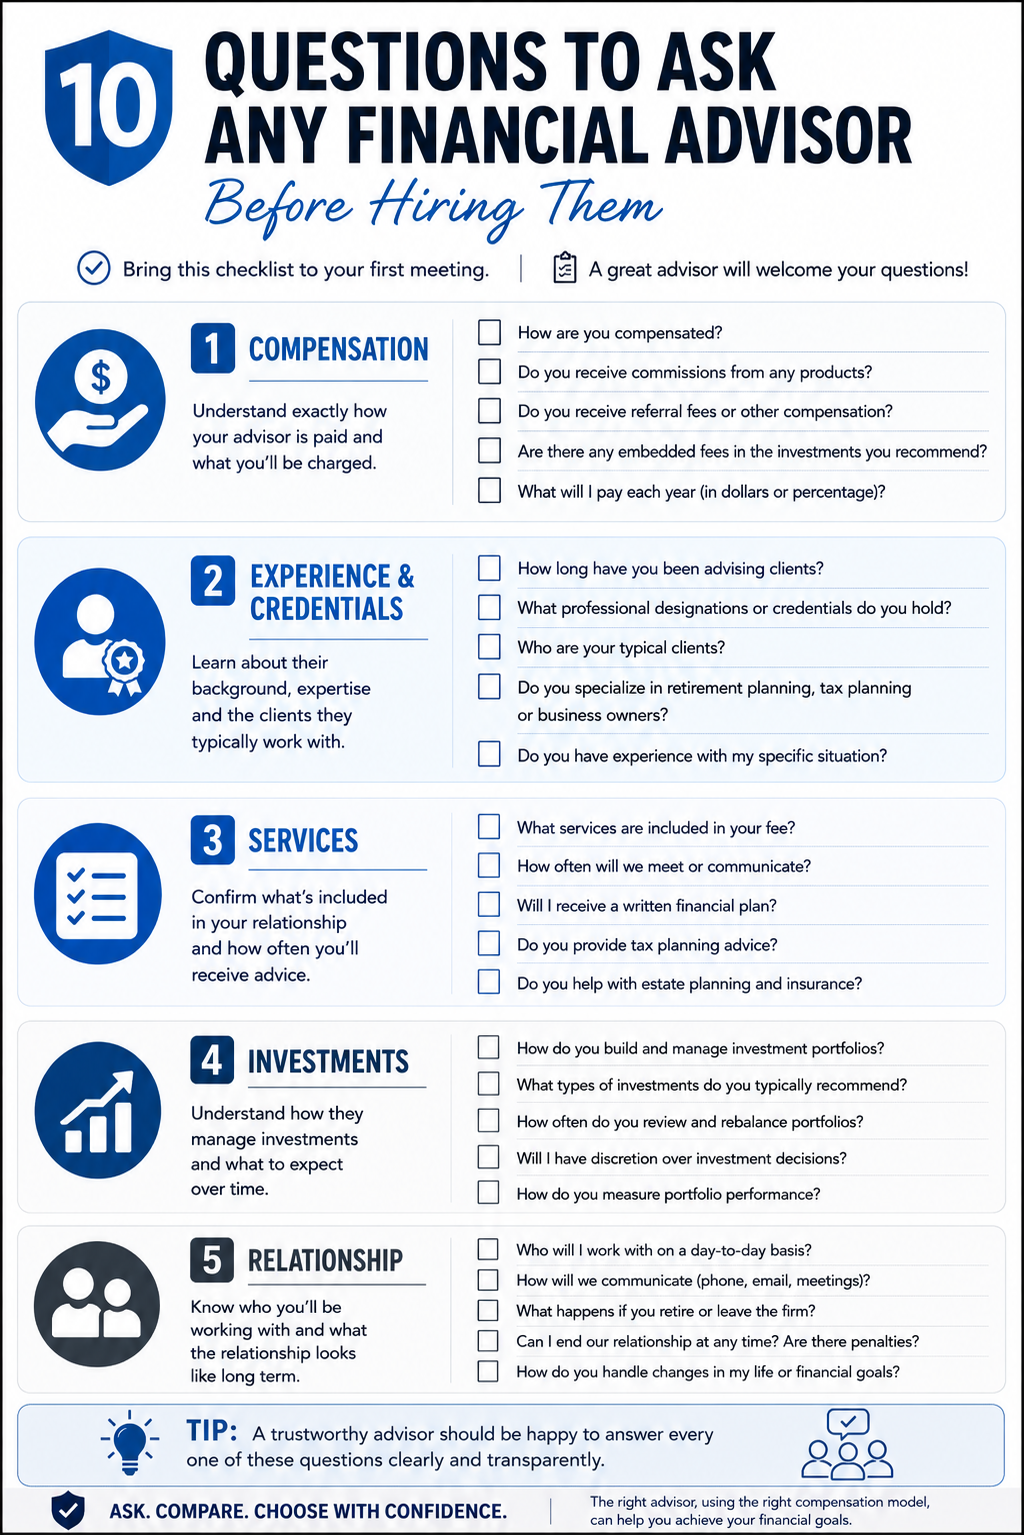
Questions to Ask Before Hiring a Financial Advisor
Bring this checklist to your first meeting.
Compensation
- How are you compensated?
- Do you receive commissions?
- Do you receive referral fees?
- Are there any embedded investment fees?
- What will I pay each year?
Credentials
- What professional designations do you hold?
- How long have you been advising clients?
- Who are your typical clients?
- Do you specialize in retirement planning, tax planning or business owners?
Services
- What's included in your fee?
- How often will we meet?
- Do you provide written financial plans?
- Will you review my investments?
- Do you help with taxes and estate planning?
Investments
- How do you build portfolios?
- What investments do you typically recommend?
- How often do you rebalance portfolios?
- Will I receive ongoing reviews?
Relationship
- Who will I work with?
- How will we communicate?
- What happens if my advisor retires or leaves the firm?
- Can I end the relationship at any time?
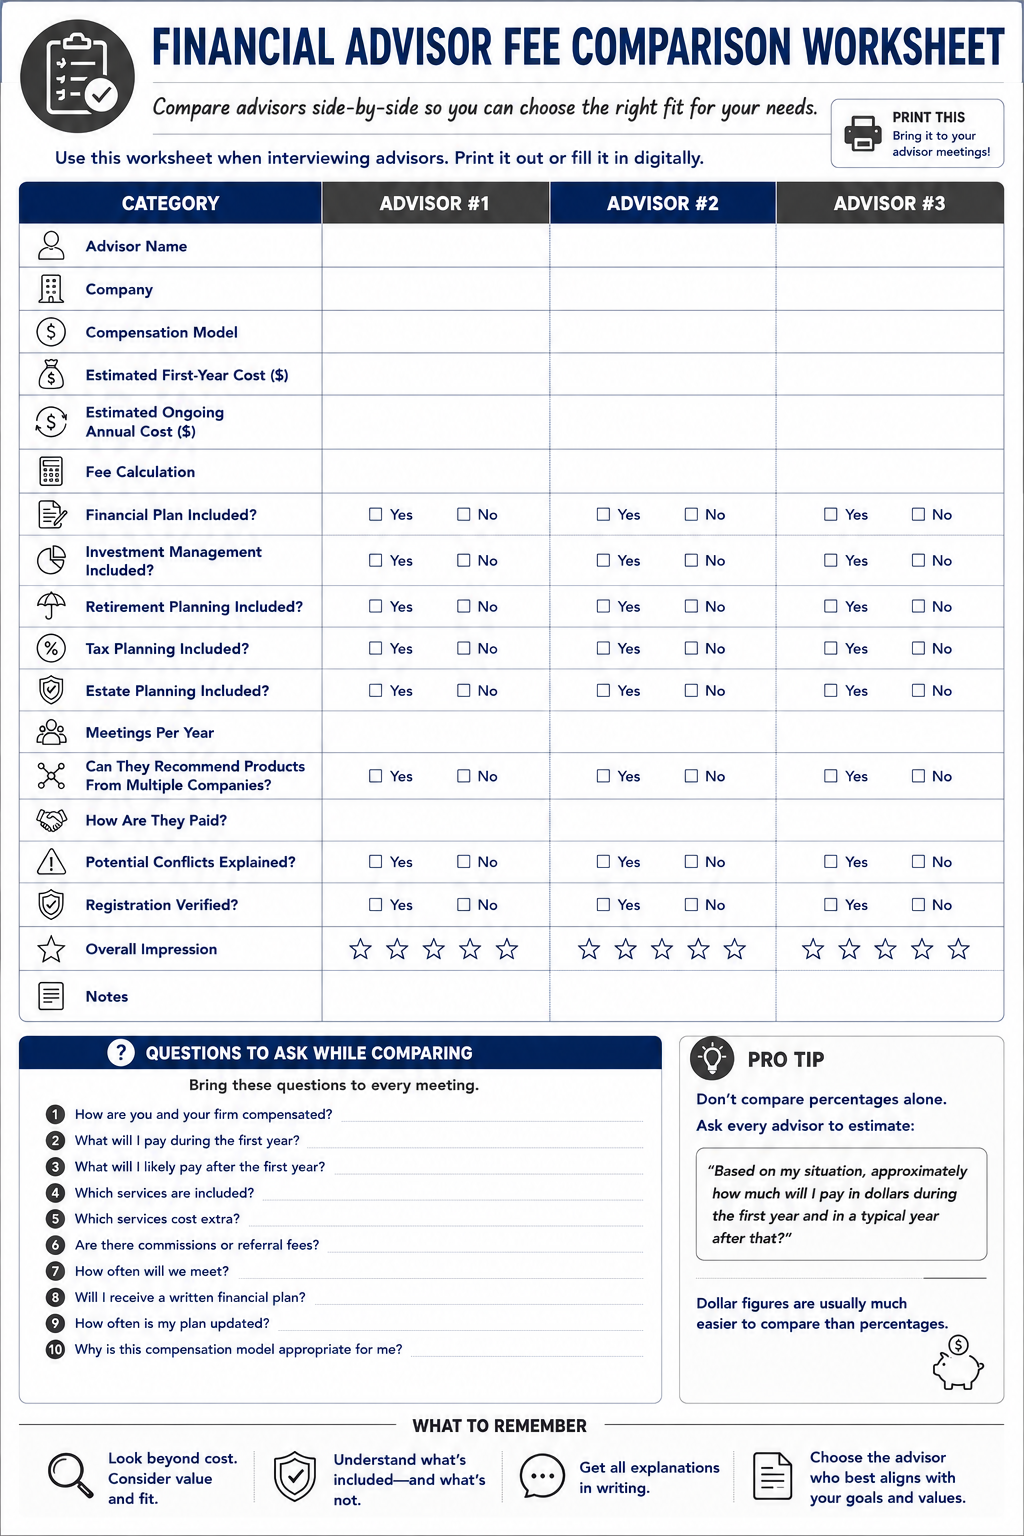
How to Compare Financial Advisor Fees
Finding the lowest fee isn't always the goal. Instead, compare what you're paying, what's included, and how the advisor is compensated.
Print this worksheet below or use it while interviewing advisors.
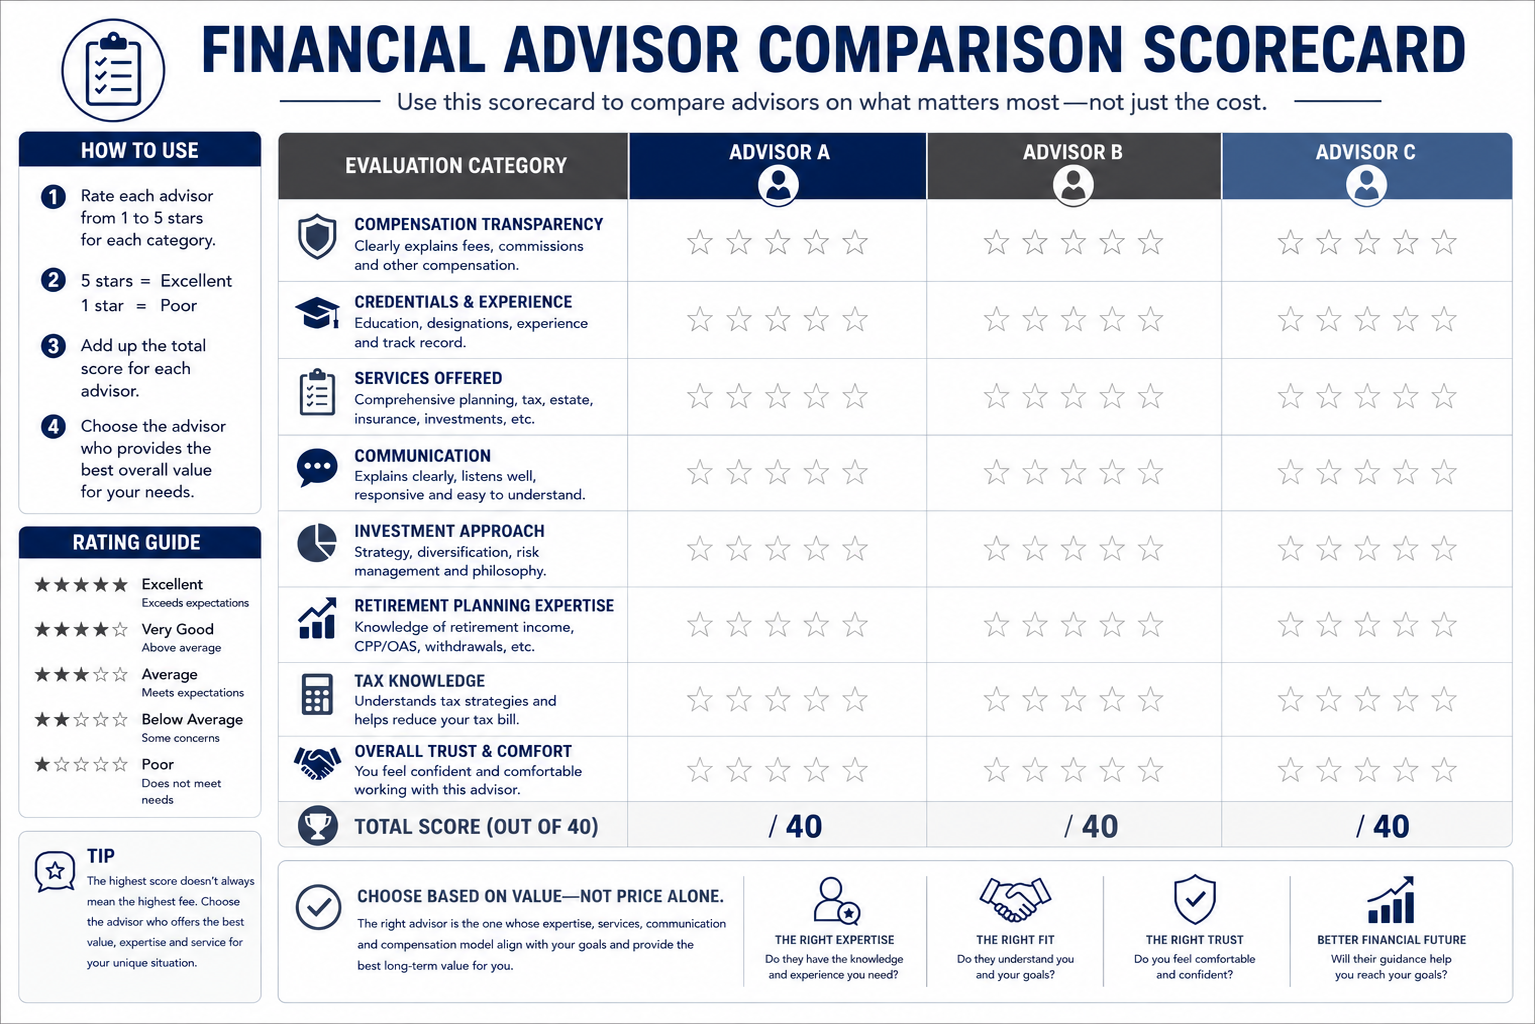
How to Compare Financial Advisors Beyond Their Fees
Understanding how a financial advisor gets paid is important, but it shouldn't be the only factor you consider.
A lower fee doesn't automatically mean better value, just as a higher fee doesn't automatically mean better advice.
Instead, compare advisors using a combination of cost, expertise, services and overall fit.
1. Credentials & Qualifications
Start by asking about professional designations.
Some common Canadian credentials include:
Designation | Focus |
CFP® (Certified Financial Planner) | Comprehensive financial planning |
QAFP® (Qualified Associate Financial Planner™) | Foundational financial planning |
CFA® (Chartered Financial Analyst) | Investment management and portfolio analysis |
CIM® (Chartered Investment Manager) | Portfolio management |
A designation alone doesn't guarantee quality, but it does demonstrate education, examination requirements and continuing professional development.
2. Services Included
Two advisors may charge exactly the same fee while offering completely different services.
Ask whether their fee includes:
- Retirement planning
- Tax planning
- Estate planning
- Insurance analysis
- Cash flow planning
- Investment management
- Ongoing reviews
- Access between meetings
One advisor may simply manage investments.
Another may become your long-term financial partner.
3. Fiduciary Responsibility
Many Canadians search for a "fiduciary financial advisor."
While the term is important, it's also frequently misunderstood.
Rather than asking only:
"Are you a fiduciary?"
Also ask:
- Are you legally obligated to act in my best interest?
- How are potential conflicts managed?
- How are recommendations documented?
- Why are you recommending this strategy instead of another?
Transparency often tells you more than labels alone.
4. Communication Style
The best financial plan in the world isn't helpful if you don't understand it.
Ask yourself:
- Do they explain concepts clearly?
- Do they answer questions patiently?
- Do they educate instead of sell?
- Do they simplify complex topics?
You'll likely work with this advisor for many years.
Communication matters.
5. Fee Transparency
A trustworthy advisor should clearly explain:
- What you'll pay
- How they'll be paid
- What's included
- What isn't included
- Whether additional costs exist
If the fee structure feels confusing, ask questions until you're comfortable.
6. Technology & Client Experience
Today's advisors often provide:
- Client portals
- Digital document storage
- Online scheduling
- Virtual meetings
- Financial planning software
- Secure messaging
Convenience isn't everything, but it certainly improves the client experience. Print this scoreboard sheet below for your reference when comparing financial advisors.
Red Flags to Watch For
Most advisors are honest professionals who genuinely want to help their clients.
However, there are situations where you should slow down and ask more questions.
Watch for these warning signs:
- They can't clearly explain how they're compensated.
- He or she pressures you to make an immediate decision.
- They guarantee investment returns.
- The advisor dismisses questions about fees.
- They're recommending products before understanding your goals.
- Investment risks can't be explained by them.
- They avoid providing written recommendations.
- The advisor promises market-beating performance with certainty.
No advisor can predict the future or guarantee returns.
A trustworthy advisor will be upfront about both opportunities and risks.
Green Flags to Look For
Just as there are warning signs, there are also positive indicators.
Look for advisors who:
- Clearly explain how they're paid.
- Listen more than they talk.
- Ask thoughtful questions about your goals.
- Explain recommendations in plain language.
- Encourage questions.
- Provide written financial plans.
- Disclose all fees.
- Set realistic expectations.
- Focus on long-term planning rather than short-term performance.
Conclusion
Choosing a financial advisor isn't just about investment returns, it's about finding someone whose expertise, services and compensation model align with your financial goals.
Some Canadians benefit most from a fee-only planner who provides objective advice for a one-time financial plan. Others prefer an advisor who offers ongoing investment management through an assets-under-management (AUM) model.
Still others value the convenience of working with a fee-based or commission-based advisor who can provide both planning and product implementation.
There is no universal "best" compensation model.
The best choice depends on:
- Your financial goals
- The complexity of your finances
- Whether you want ongoing advice or a one-time plan
- How you prefer to pay for professional advice
The most important takeaway is simple:
Always understand how your advisor is compensated before you become a client.
A good advisor will explain their fees clearly, answer your questions openly and help you understand exactly what services you'll receive in return.
Ready to Find the Right Financial Advisor?
Whether you're looking for a fee-only financial planner, an advisor who offers ongoing wealth management, or simply a second opinion, we'll help match you with a professional whose compensation model and expertise fit your needs.
-> Complete our free advisor matching questionnaire to get started.
Frequently Asked Questions About Financial Advisor Fees
How do financial advisors get paid in Canada?
Financial advisors in Canada are typically compensated in one or more of the following ways:
- Fee-only
- Fee-based
- Commission
- Assets Under Management (AUM)
- Hourly fees
- Flat or project fees
The compensation model varies by advisor and firm. Before becoming a client, ask your advisor exactly how they are paid and request a clear explanation of all fees, commissions and any other compensation they receive.
What is the difference between fee-only and fee-based financial advisors?
A fee-only advisor is compensated directly by clients and generally does not receive commissions from financial products.
A fee-based advisor also charges client fees but may earn commissions from certain investments or insurance products.
Although the terms sound similar, they describe different compensation models.
Are commission-based financial advisors bad?
No.
Many commission-based advisors provide excellent financial advice and long-term service.
The important consideration isn't whether an advisor earns commissions—it's whether they're transparent about their compensation, explain their recommendations clearly and provide advice that's appropriate for your situation.
Is fee-only financial advice worth it?
For many Canadians, yes.
Fee-only advice can be particularly valuable if you're looking for:
- Comprehensive financial planning
- Retirement planning
- Tax planning
- Estate planning
- Objective recommendations
However, every situation is different. The best compensation model depends on your goals, the complexity of your finances and the services you need.
Do I pay financial advisor fees directly?
Sometimes.
Depending on the compensation model, you may:
- Pay directly by invoice
- Pay hourly
- Pay a flat planning fee
- Pay an annual percentage of assets under management (AUM)
In other cases, advisor compensation may be built into investment or insurance products.
Always ask for a full breakdown of the costs you'll pay.
How much does a financial advisor cost?
Costs vary significantly depending on the services provided.
Typical Canadian ranges include:
Service | Typical Cost |
Hourly Advice | $150–$500/hour |
Comprehensive Financial Plan | $1,000–$5,000+ |
Annual Retainer | $2,000–$10,000+ |
Assets Under Management | Approximately 0.50%–2.00% annually |
Fees may be higher for more complex financial situations.
Is a financial planner the same as a financial advisor?
Not always.
While the terms are often used interchangeably, financial planners generally focus on comprehensive financial planning, while financial advisors may provide investment management, insurance advice or both.
Some professionals provide both services.
Can I hire a financial planner for just one meeting?
Yes.
Many fee-only and hourly financial planners offer one-time consultations for topics such as:
- Retirement planning
- Tax planning
- Investment reviews
- Second opinions
- Cash flow planning
This can be an excellent option if you don't require ongoing portfolio management.
Which compensation model has the fewest conflicts of interest?
Many investors view fee-only compensation as having fewer potential conflicts because advisors are paid directly by clients rather than by product providers.
That said, no compensation model completely eliminates potential conflicts. Transparency, professionalism and acting in the client's best interest remain essential regardless of how an advisor is compensated.
Should I ask my financial advisor how they get paid?
Absolutely.
In fact, it should be one of the first questions you ask.
Understanding an advisor's compensation helps you:
- Compare advisors more effectively
- Understand the total cost of advice
- Identify potential conflicts of interest
- Choose a compensation model that aligns with your preferences
Check out our full guide on [how financial advisors get paid].
CIRO states that investors have a right to clear information about the fees and costs they pay and what those charges are for. Ask for the complete fee schedule and an estimate of the total annual cost in both dollars and percentages.
Sources
Canadian Investment Regulatory Organization (CIRO) on advisor compensation, fees and investor questions.
https://www.ciro.ca/office-investor/investing-basics/selecting-advisor
Financial Consumer Agency of Canada (FCAC) on how Canadians pay financial advisors and the importance of understanding compensation.
Reviewed by: FeeOnlyFinancial.ca Editorial Team